Golar LNG Maintains Buy Rating Amid Argentina Progress and Q3 Earnings
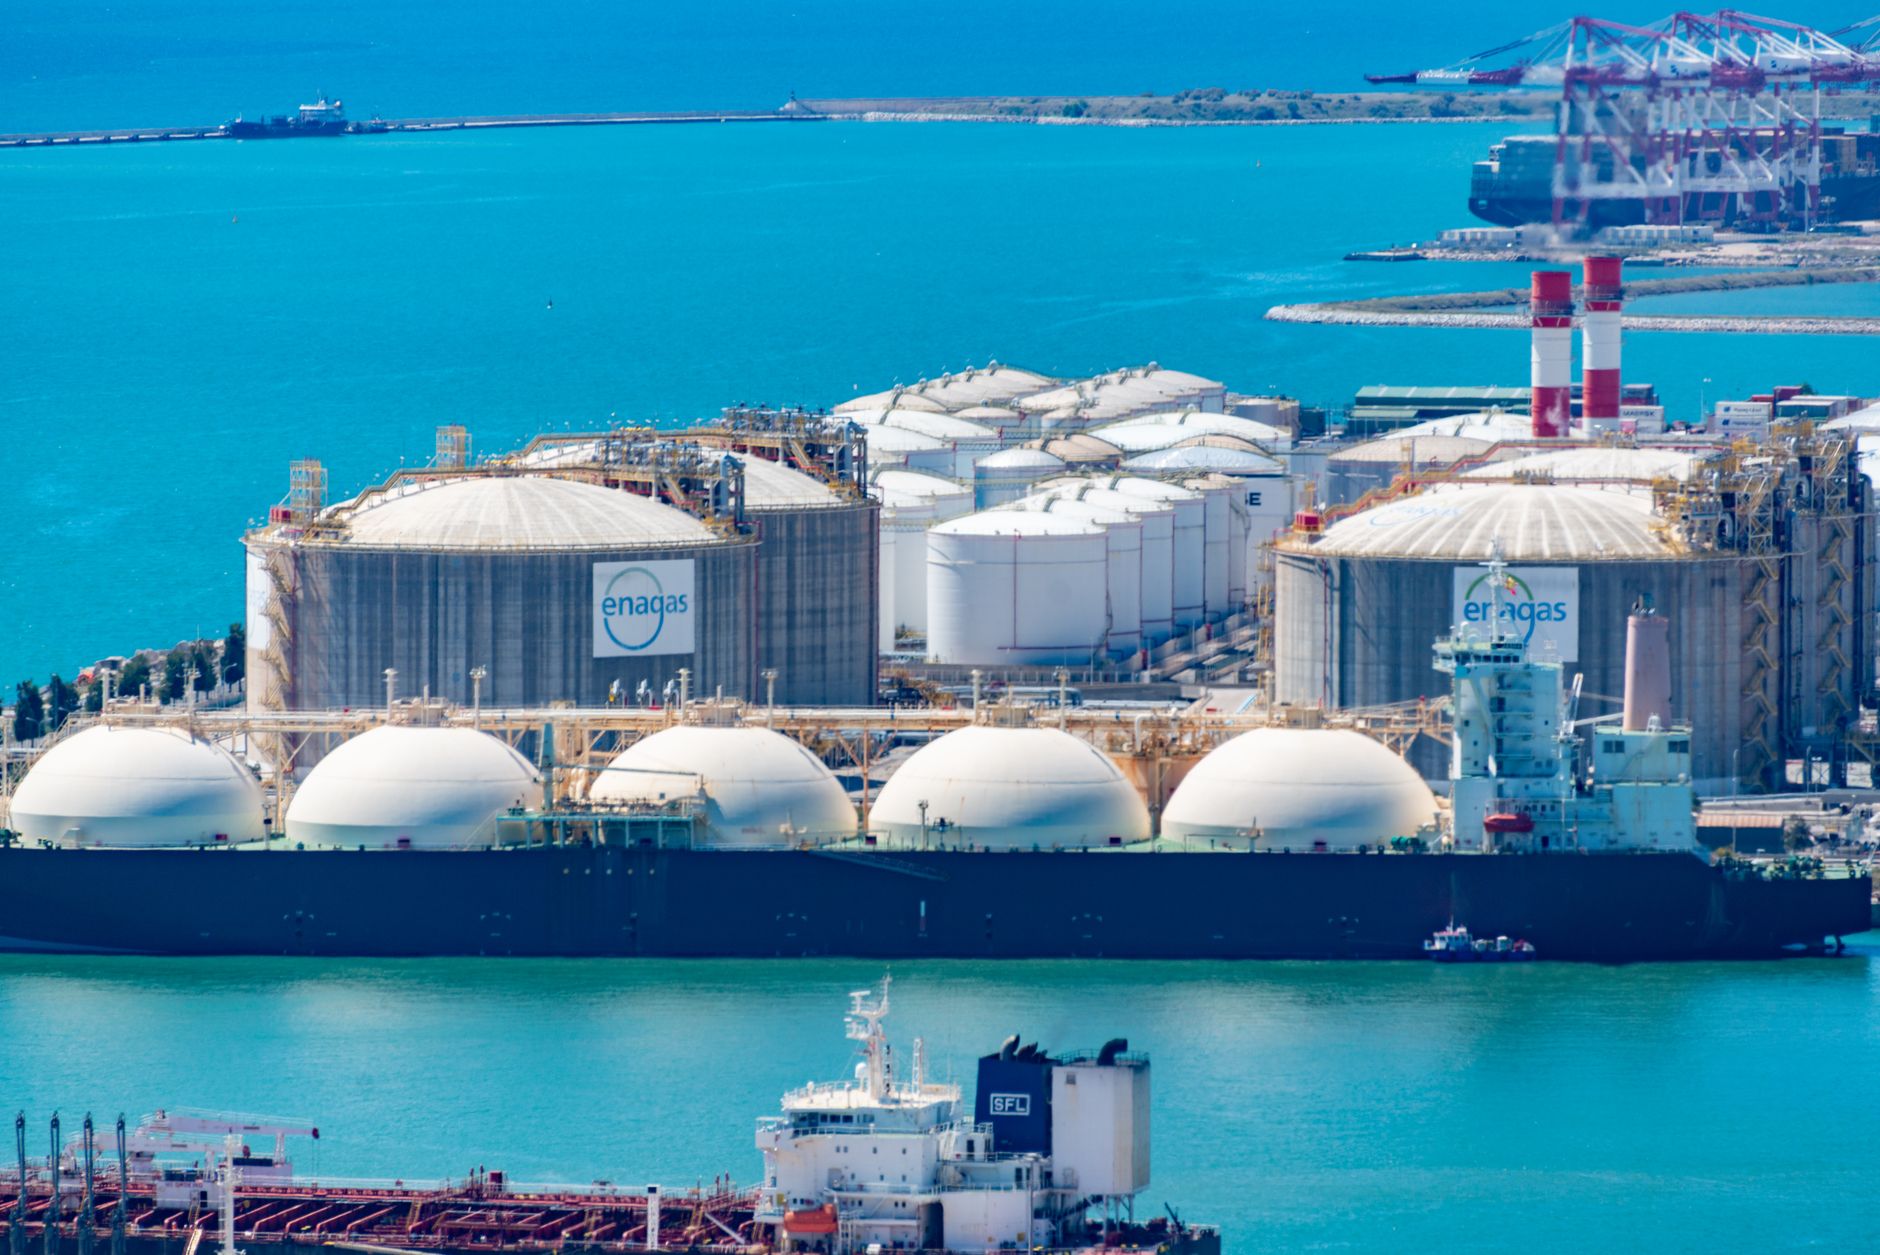
Golar LNG continues to present a compelling investment opportunity despite posting softer financial results in the third quarter. While near-term earnings faced headwinds, the broader strategic trajectory of the company remains highly positive. In particular, significant milestones in South America have reinforced confidence in the long-term outlook for maritime energy infrastructure.
Financial Performance Overview
The recent quarterly financial report highlighted certain operational challenges that impacted short-term profitability. Market observers noted that revenue and earnings figures fell slightly below consensus expectations. However, experienced analysts look beyond immediate quarterly fluctuations to evaluate the fundamental value proposition of the enterprise. Temporary dips in financial metrics often create attractive entry points for long-term investors who focus on secular growth drivers.
Strategic Advances in South America
The primary catalyst supporting the favorable investment stance is the substantial progress achieved in Argentina. Collaborations and regulatory advancements related to floating liquefied natural gas infrastructure in the region signify major operational headway. These developments pave the way for long-term revenue generation and solidify the market position of the firm in key global energy corridors.
Unlocking Long-Term Value
Floating liquefaction technology offers unique flexibility and cost advantages compared to traditional land-based facilities. By deploying these advanced vessels, the organization can monetize gas reserves that might otherwise remain stranded. The ongoing projects in South America serve as a prime example of this model in action, translating technical expertise into sustainable commercial success.
Navigating Sector Challenges
The liquefied natural gas sector operates in a dynamic environment characterized by fluctuating commodity prices and shifting geopolitical landscapes. Despite these inherent complexities, the targeted asset portfolio of the company provides a robust buffer. Long-term contracts and specialized vessel deployment help mitigate exposure to spot market volatility, ensuring steady cash flow generation over extended periods.
Outlook for Investors
Investors evaluating the maritime energy space must weigh current financial reports against future growth potential. Although the recent third-quarter figures were weaker than anticipated, the overarching narrative remains intact. Strategic execution in international markets, particularly in South America, outweighs temporary earnings softness.
Conclusion
In summary, the steady advancement of key projects in Argentina provides strong justification for maintaining a positive outlook on the stock. The ability to secure major international agreements demonstrates the resilience and competitive advantage of the enterprise. For those with a forward-looking perspective, the current market pricing reflects a favorable risk-reward balance.
RELATED STORIES
stock-market
Federal Reserve Communication Strategy Sparks Debate Amid Policy Shifts
Explore the ongoing debate surrounding Federal Reserve official communications, forward guidance, and monetary policy transparency.
stock-market
Erasca Receives Buy Rating Following KRAS Expansion and Bristol Myers Squibb Partnership
Discover why Erasca earned a Buy rating due to its expanded KRAS targeting pipeline, ERAS-4001, and strategic collaboration with Bristol Myers Squibb.
stock-market
Healthcare Stocks Plunge Amid New Medicare Policy Proposals
Major healthcare and insurance stocks face sharp declines following the introduction of a new Medicare for All legislative proposal.