Micron Valuation: Why A 5x PE Ratio Requires Deeper Analysis
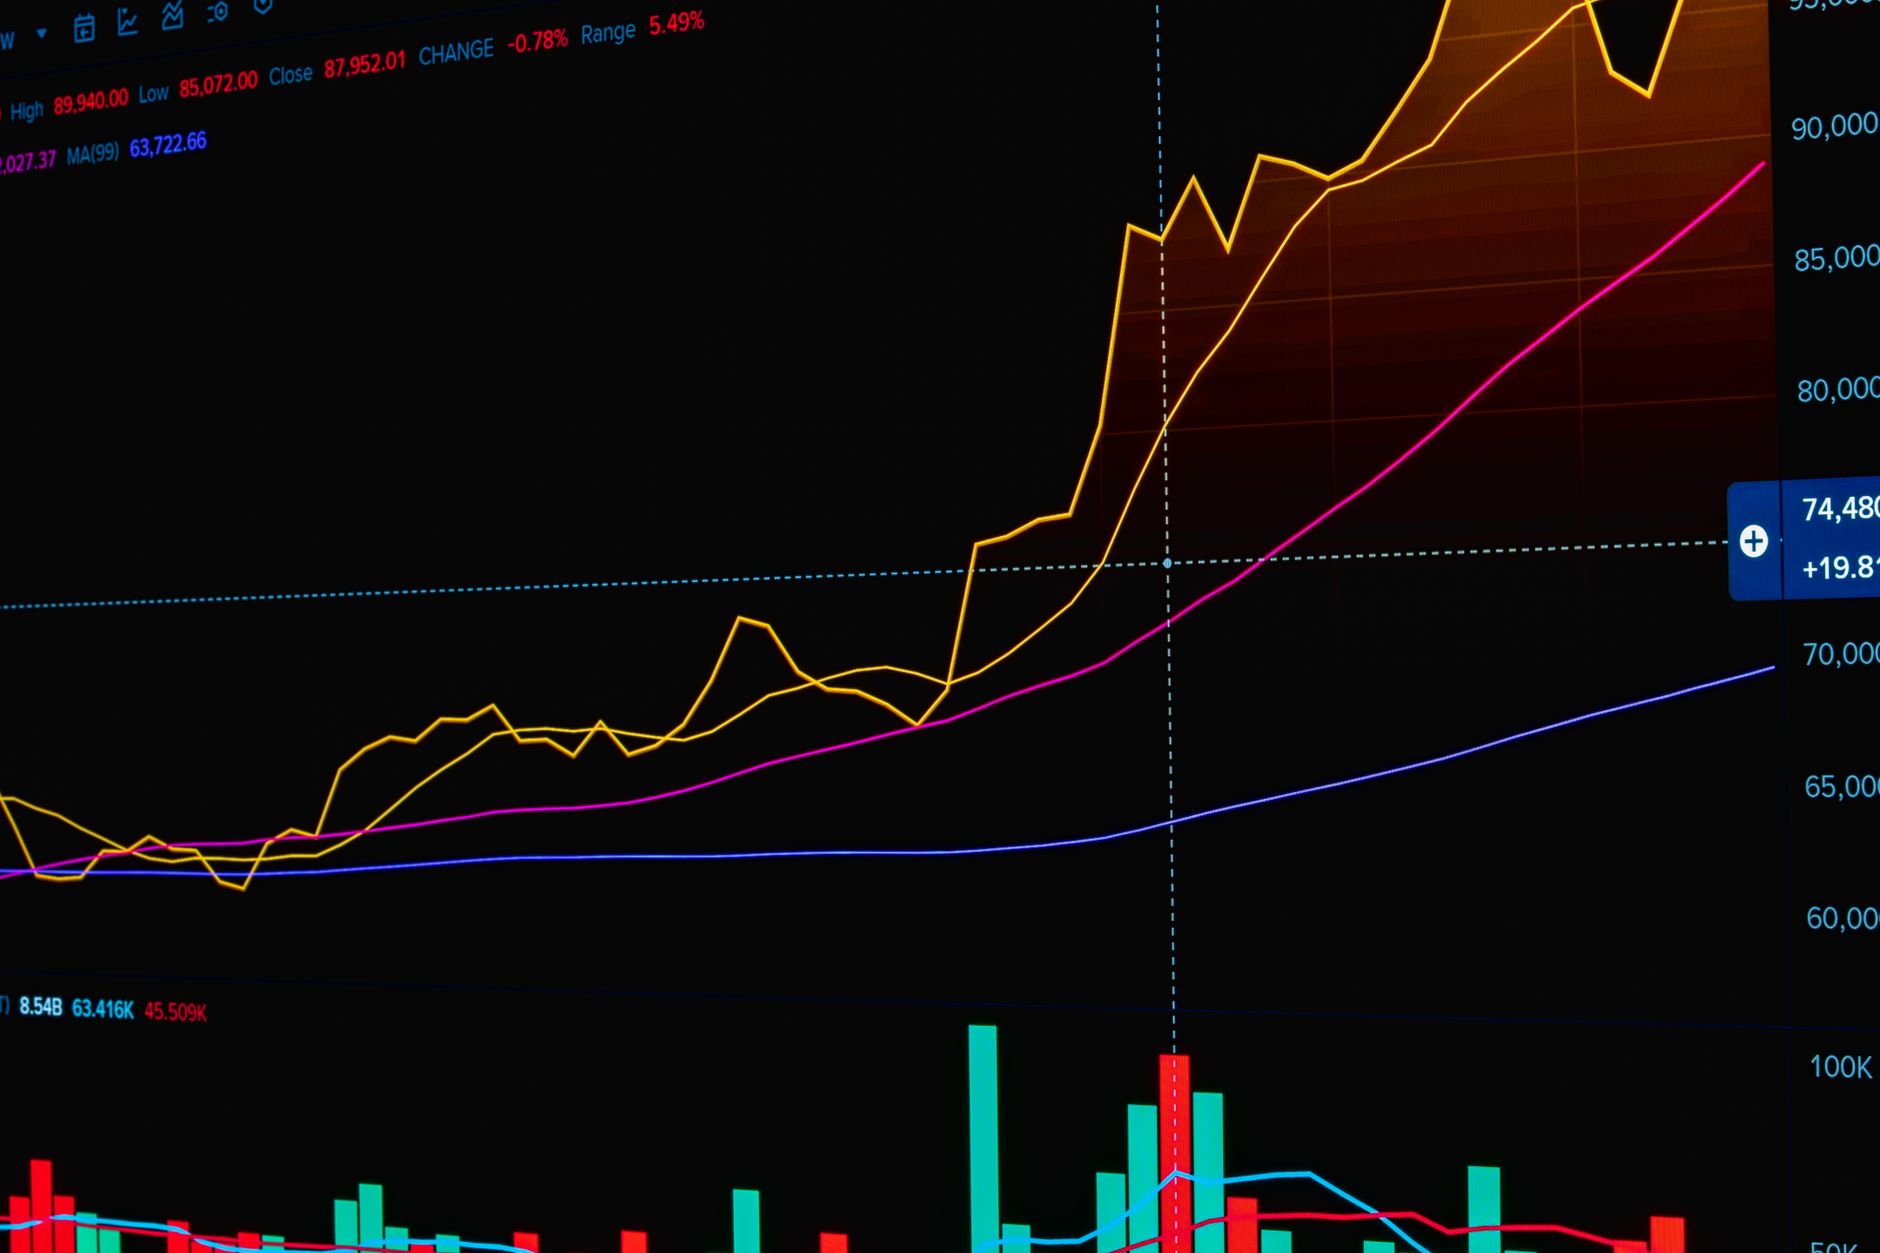
Evaluating Semiconductor Stocks Through A Fresh Lens
When examining the current financial metrics of leading memory chip manufacturers, certain numbers immediately capture the attention of market participants. Among these figures, an exceptionally low price-to-earnings ratio often stands out as a primary indicator of potential value. For many investors, a headline multiple of five times earnings suggests that an equity is severely undervalued and represents a compelling acquisition opportunity.
However, the semiconductor industry operates within a framework of extreme cyclicality, shifting supply dynamics, and heavy capital expenditure requirements. Consequently, relying solely on a trailing or forward earnings multiple can obscure the underlying operational realities of these complex businesses. A thorough investigation reveals that surface-level cheapness frequently masks structural complexities that demand a more nuanced valuation approach.
Understanding The Cyclical Nature Of Memory Markets
To properly contextualize profitability within the semiconductor sector, one must acknowledge the inherent volatility of memory demand. Pricing power for dynamic random-access memory and flash storage fluctuates dramatically depending on global macroeconomic conditions, enterprise data center expansion, and consumer electronics demand.
During periods of robust pricing, manufacturing enterprises often experience a massive surge in net income. This earnings explosion naturally depresses the price-to-earnings ratio to seemingly bargain levels. Yet, interpreting this cyclical peak profitability as a sustainable baseline can lead to significant miscalculations regarding the true intrinsic worth of the underlying enterprise.
Capital Intensity And Reinvestment Realities
Another critical factor influencing equity value is the relentless requirement for heavy capital investment. Maintaining a competitive edge in advanced fabrication nodes necessitates billions of dollars in ongoing expenditures for cutting-edge machinery and facility upgrades.
Because these assets depreciate rapidly and require constant modernization, a substantial portion of reported earnings must be funneled directly back into capital projects rather than returned to shareholders. This reality means that free cash flow conversion may not always align seamlessly with net income, rendering the headline valuation multiple less attractive than it initially appears.
Identifying The Underlying Investment Upside
Despite the caveats surrounding low earnings multiples, structural tailwinds continue to support a positive long-term thesis for major memory suppliers. The rapid proliferation of artificial intelligence applications, high-performance computing clusters, and data-intensive enterprise workloads has fundamentally transformed the demand profile for advanced memory components.
Modern artificial intelligence infrastructure relies heavily on specialized high-bandwidth memory to process massive datasets efficiently. This specialized product category commands superior profit margins and enjoys structural demand that is less vulnerable to traditional consumer electronics downturns.
As these high-margin segments expand as a percentage of total revenue, the overall business mix shifts toward greater stability. This transition helps mitigate the severe troughs historically associated with the memory industry, potentially justifying a higher valuation multiple over the long run.
Strategic Considerations For Market Participants
Navigating cyclical equities requires balancing near-term valuation metrics against long-term structural trends. While a low price-to-earnings ratio should never be accepted at face value, it often accompanies companies that possess the financial strength and technological leadership to navigate cyclical downturns successfully.
Investors examining these opportunities must look beyond standard accounting ratios and focus on technological differentiation, balance sheet resilience, and secular growth drivers. By factoring in the capital-intensive nature of advanced fabrication alongside the accelerating demand for high-performance memory, market participants can better gauge where the genuine upside resides.
Conclusion On Semiconductor Valuation
Ultimately, headline multiples serve merely as a starting point for rigorous financial analysis rather than a definitive conclusion. A thorough examination demonstrates that while current earnings ratios require careful interpretation, the broader technological landscape continues to offer promising avenues for long-term growth and capital appreciation.
RELATED STORIES
stock-market
Velocity Financial Q3 2026 Earnings: Performance and Financial Overview
Analyze Velocity Financial Inc Q3 2026 earnings presentation results, financial performance metrics, and key operational updates.
stock-market
Regeneron Director George Sing Offloads Stock Valued at Over $20 Million
Regeneron Pharmaceuticals director George Sing recently executed a major stock sale, offloading company shares worth approximately $20.3 million.
stock-market
Why a Prolonged War in Iran is the Ultimate Market Black Swan
Discover why financial strategists warn that an extended conflict involving Iran remains largely unpriced by global stock markets.