Financial Planning for Couples with a Significant Age Gap
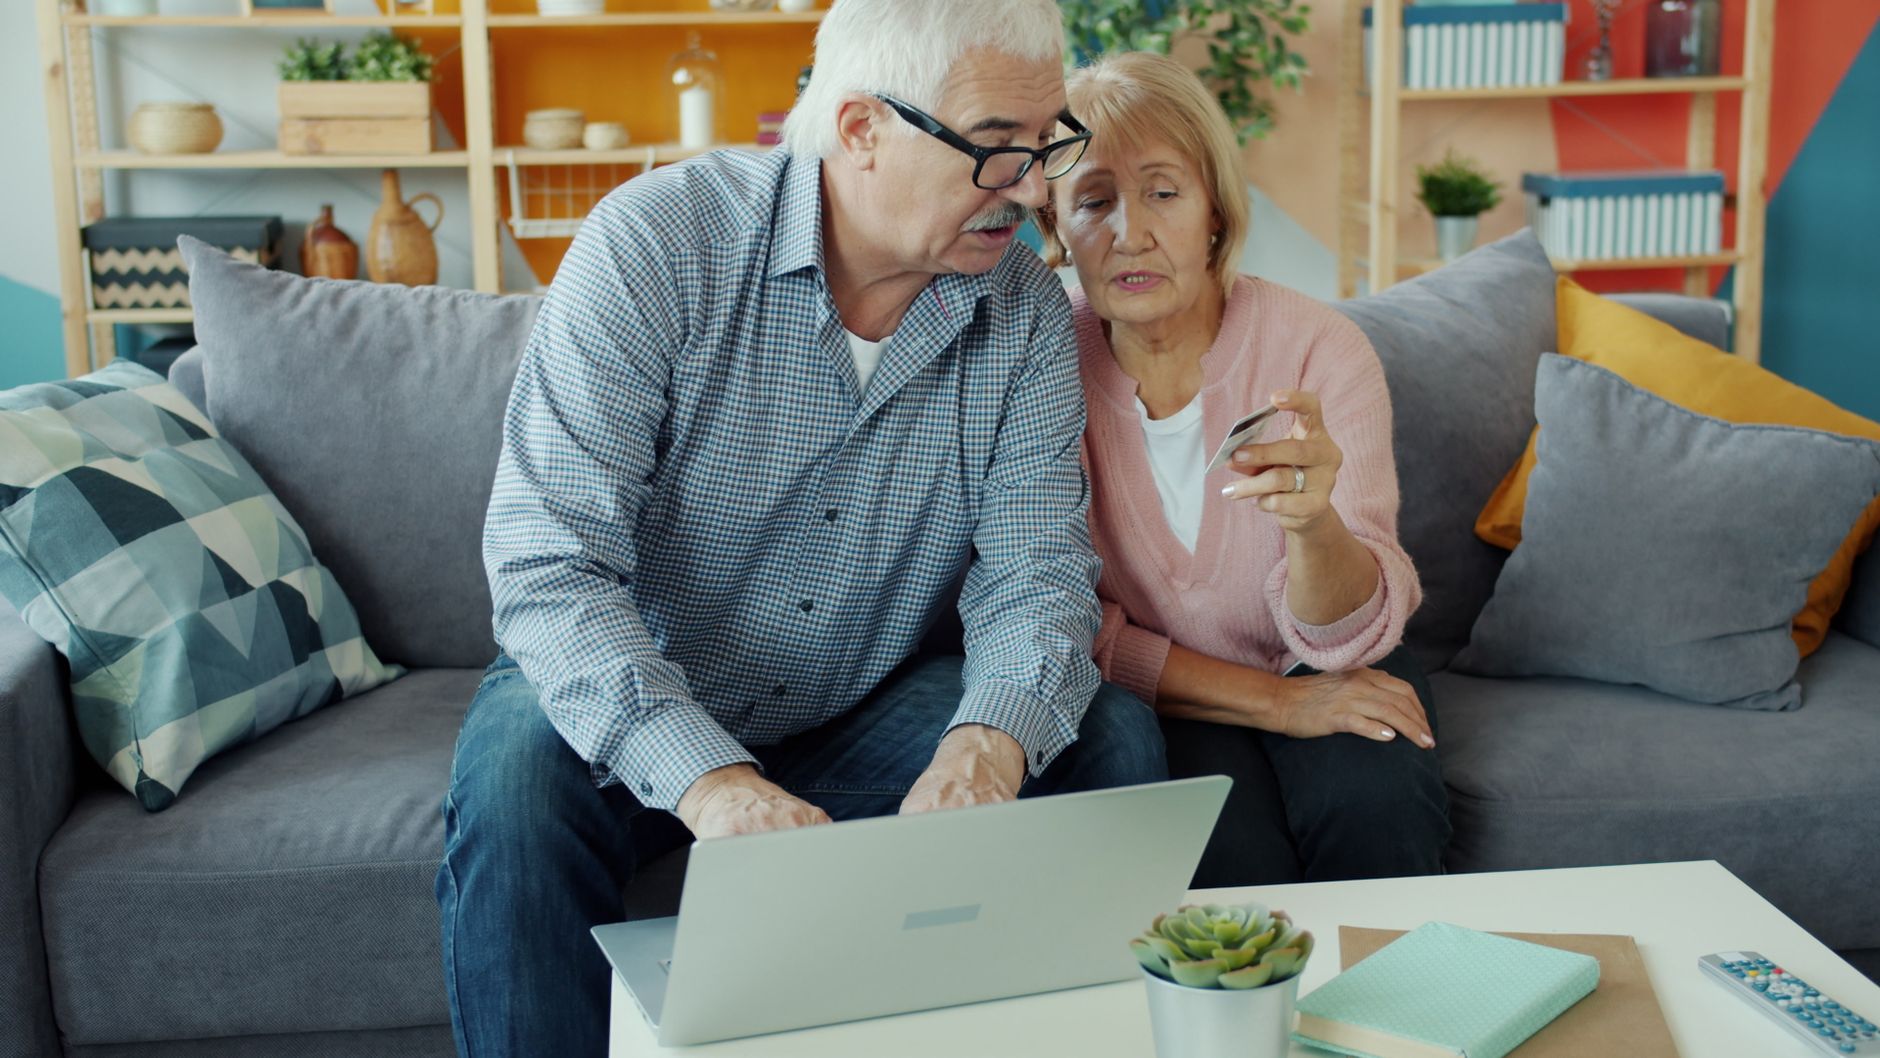
Navigating a relationship with a substantial age difference brings unique joys, but it also introduces complex financial challenges that require careful preparation. When partners are separated by a decade or more, their life timelines do not align neatly. This misalignment is particularly evident when looking toward the future, as these relationships demand synchronized planning for two entirely separate retirement paths.
Introduction to Age Gap Financial Planning
Traditional financial advice often assumes that partners will retire around the same time and share a synchronized golden age. However, for partnerships where one person is significantly older, that assumption falls apart immediately. The older partner may be ready to leave the workforce while the younger partner still has decades of career earnings ahead. Recognizing this reality is the first step toward building a secure financial foundation.
The Timeline Disconnect
The most prominent hurdle for age gap couples is the timeline disconnect. When one individual reaches retirement age, the other might still be at the peak of their earning power or managing major expenses like mortgages and children's education. This means the older partner will transition to a fixed income while the younger partner continues to earn and spend at a different level. Coordinating lifestyle expectations during this transitional phase is critical to avoid resentment or financial strain.
Planning for Two Distinct Retirements
Because retirement will not happen simultaneously, couples must budget for two separate retirements rather than a single joint exit from the workforce. The older partner will begin drawing down savings, utilizing social security benefits, and relying on pensions much earlier. Meanwhile, the younger partner must continue funding their own retirement accounts, often for an extra ten to fifteen years. This dual trajectory requires a strategic approach to investment portfolios, ensuring that the assets supporting the older partner do not compromise the growth needed for the younger partner's future.
Healthcare and Insurance Realities
Healthcare is another major concern for couples with a significant age difference. The older partner may become eligible for government-sponsored healthcare programs years before the younger partner. During the gap years, the younger partner may need to secure private health insurance, which can be a substantial out-of-pocket expense. Furthermore, long-term care planning becomes a pressing issue much sooner for the older partner, requiring dedicated funds that will not deplete the resources the younger partner will need later in life.
Social Security and Pension Maximization
Timing the collection of social security benefits and pensions requires sophisticated coordination in age gap relationships. Claiming strategies should account for the survivor benefits that the younger partner might eventually receive. Maximizing the older partner's payouts while allowing the younger partner's retirement accounts to compound undisturbed can significantly strengthen the household's long-term financial security.
Communication and Professional Guidance
Open and honest communication about money is the bedrock of any successful partnership, but it is doubly important when timelines differ. Both individuals must feel heard regarding their retirement dreams, risk tolerances, and savings goals. Consulting a fee-only financial planner who specializes in complex family dynamics can provide an objective roadmap. A professional can help design a portfolio that balances immediate retirement income needs with long-term growth objectives.
Conclusion
Relationships defined by a large age gap require deliberate financial foresight. By acknowledging the reality of two distinct retirements, addressing healthcare costs proactively, and optimizing benefit collection strategies, couples can build a resilient financial future. Careful planning ensures that both partners can enjoy their respective retirement years with peace of mind and financial stability.
RELATED STORIES
stock-market
Prosperity Bancshares Investment Analysis: Why This Regional Bank Remains Strong
Discover why financial analysts continue to favor Prosperity Bancshares as a resilient regional bank investment with strong fundamentals.
stock-market
Airbus Reaffirms Annual Delivery Goals Amid Year-End Production Push
Airbus maintains its yearly targets, banking on a significant surge in aircraft deliveries during the final quarter to meet its operational objectives.
stock-market
Stepan Company Q3 2026 Financial Results and Business Overview
Explore the Stepan Company Q3 2026 financial performance, earnings highlights, and strategic business updates based on the latest corporate earnings call.