SP 500 Catalysts: Why Japanese Monetary Policy Matters More Than Geopolitics
Understanding Market Drivers
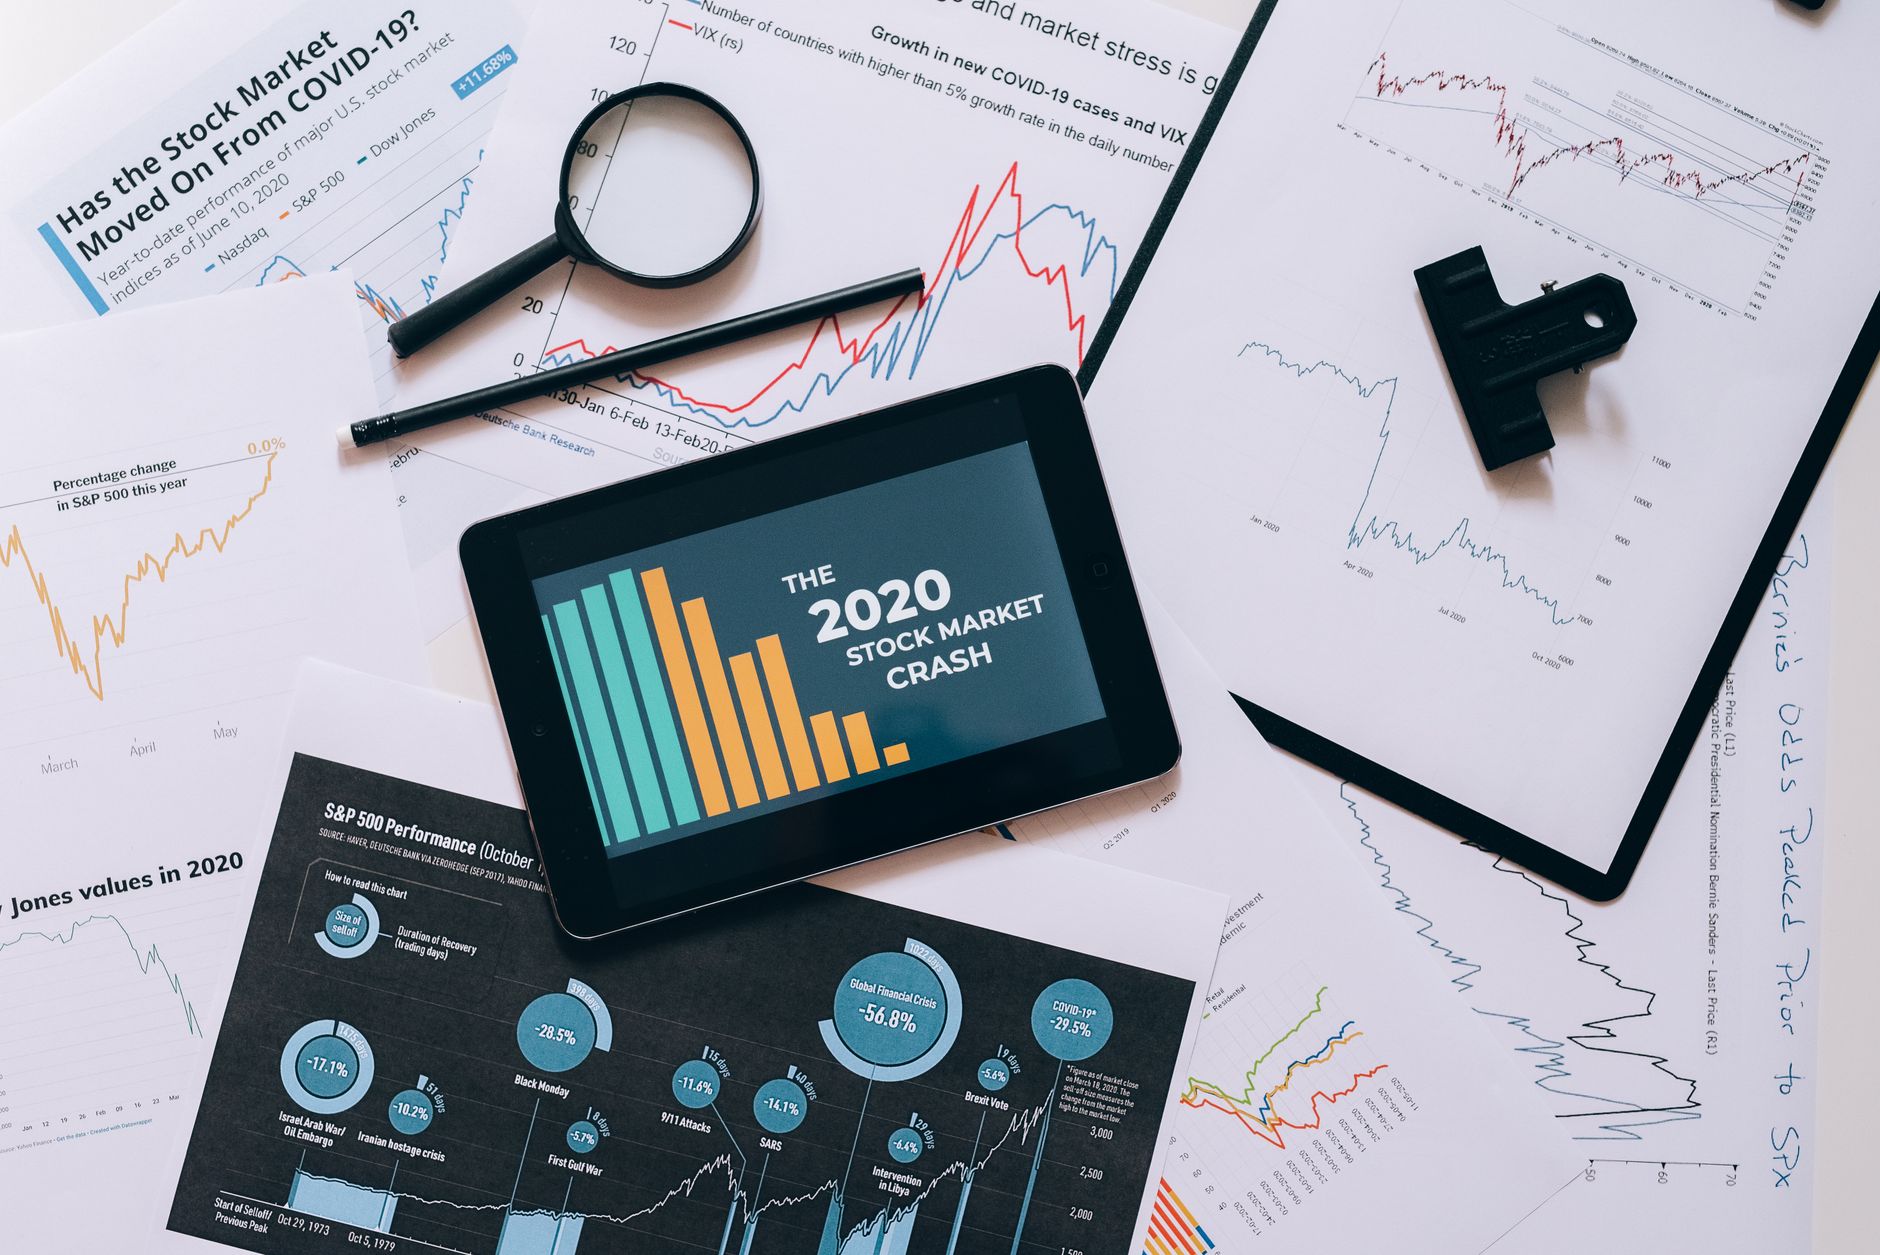
Financial markets constantly balance numerous competing narratives, attempting to price in risk and opportunity on a daily basis. Investors often fixate on dramatic geopolitical headlines, assuming that military conflicts or regional standoffs will dictate the immediate direction of major equity benchmarks. However, a deeper examination of macroeconomic fundamentals frequently reveals that monetary policy and central bank actions hold far greater sway over asset valuations than sudden geopolitical flare-ups.
The Illusion of Geopolitical Dominance
When conflicts arise involving major energy-producing regions, market participants routinely anticipate severe disruptions to global commerce and energy supplies. Tensions between the United States and Iran historically trigger immediate anxiety across global trading floors, leading to short-term spikes in volatility and safe-haven assets. Yet, historical precedence demonstrates that equity markets often absorb these shocks relatively quickly unless there is a prolonged, catastrophic impact on physical supply chains. The market mechanism is remarkably adept at pricing in geopolitical risk as transient noise rather than a permanent structural impairment to corporate earnings.
The Weight of Japanese Monetary Shifts
In contrast to the transient nature of regional conflicts, monetary policy developments originating outside the domestic economy can trigger profound, lasting ripples across international asset classes. Shifts in the stance of the central bank of Japan carry immense weight for global liquidity conditions. For decades, global investors utilized low-cost funding from the Asian nation to finance investments in higher-yielding assets worldwide, a dynamic commonly known as the carry trade. When the central bank adjusts interest rate targets or signals a pivot toward monetary normalization, the resulting unwinding of these positions forces institutional portfolio managers to reallocate capital on a massive scale.
Implications for the Benchmark Index
For the broader United States equity market, specifically the SP 500, liquidity is the primary lifeblood that supports lofty valuation multiples. When global liquidity tightens due to policy shifts in major economies overseas, the effect is felt immediately across large-cap American equities. Institutional investors may find themselves compelled to sell domestic assets to cover margin calls or liquidity requirements stemming from foreign currency fluctuations. Consequently, structural monetary adjustments abroad exert a far more pervasive influence on index performance than localized geopolitical disputes.
Navigating Complex Market Dynamics
For market participants seeking to protect and grow their capital, distinguishing between primary structural drivers and secondary noise is essential. While tracking geopolitical developments remains a necessary component of risk management, allowing those headlines to dictate long-term portfolio positioning often leads to suboptimal outcomes. Prioritizing a thorough evaluation of global liquidity trends, central bank policies, and macroeconomic data releases provides a much clearer roadmap for navigating the complexities of the modern financial landscape.
RELATED STORIES
stock-market
Prosperity Bancshares Investment Analysis: Why This Regional Bank Remains Strong
Discover why financial analysts continue to favor Prosperity Bancshares as a resilient regional bank investment with strong fundamentals.
stock-market
Airbus Reaffirms Annual Delivery Goals Amid Year-End Production Push
Airbus maintains its yearly targets, banking on a significant surge in aircraft deliveries during the final quarter to meet its operational objectives.
stock-market
Stepan Company Q3 2026 Financial Results and Business Overview
Explore the Stepan Company Q3 2026 financial performance, earnings highlights, and strategic business updates based on the latest corporate earnings call.